Loan Finance Online :: News
SHARE

Share this news item!

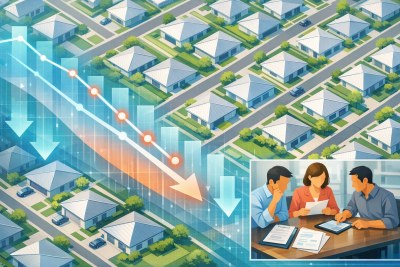
Record fall in new home lending reshapes the finance conversation

Investor demand has dropped sharply, but owner-occupiers and first-home buyers still face tighter borrowing conditions

Record fall in new home lending reshapes the finance conversation?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Australia’s home lending market has delivered a sharp warning signal, with new Australian Bureau of Statistics figures showing the number of new dwelling loan commitments fell 15.0 per cent in the September quarter 2026.
The fall was led by investors, but the broader message for borrowers is wider: higher rates, changing tax settings and softer property expectations are now influencing both lender caution and buyer confidence.

The ABS reported that the value of new dwelling loan commitments fell 15.5 per cent to $81.2 billion over the quarter, while the number of investor commitments dropped 30.6 per cent. Owner-occupier lending also weakened, falling 5.3 per cent, and first-home buyer commitments were down 8.6 per cent. These figures exclude refinancing, so they point to new purchase and construction activity rather than borrowers simply switching lenders.

For borrowers, the immediate issue is not just whether fewer people are buying property. A weaker lending market can change expectations around property prices, competition at auctions and lender appetite, but it does not automatically make finance easier to obtain. Lenders still assess income, living expenses, existing debts, credit history and buffers before deciding whether a loan appears affordable. That makes loan eligibility a central consideration even in a cooler market.

The investor retreat is particularly important because investor finance has often added momentum to established property markets. When that demand slows, some owner-occupiers may face less competition, especially in areas where investors had been active. However, softer prices can also affect valuations, deposit requirements and the amount a lender is prepared to advance against a property. A lower purchase price does not remove the need for a realistic repayment plan.

There are several practical points borrowers may wish to keep in mind:

  • Advertised borrowing limits may be less useful than a conservative budget that allows for higher repayments, insurance, rates and maintenance.
  • First-home buyers should distinguish between a lower purchase price and a loan structure that remains manageable over time.
  • Investors may need to revisit cash-flow assumptions, tax treatment, vacancy risk and the possibility of weaker capital growth.
  • Anyone comparing home loans should look beyond the headline rate to fees, features, repayment flexibility and total cost.

The latest data does not prove where property prices or interest rates will move next, and lending conditions can shift quickly. It does show, however, that the finance market is no longer being driven by the same strong demand that characterised earlier parts of the cycle. For households and small business owners using property as part of wider financial planning, the key lesson is to test assumptions carefully before taking on long-term debt.

Published:Thursday, 12th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

Record fall in new home lending reshapes the finance conversation
12 Nov 2026: Paige Estritori
Australia’s home lending market has delivered a sharp warning signal, with new Australian Bureau of Statistics figures showing the number of new dwelling loan commitments fell 15.0 per cent in the September quarter 2026. The fall was led by investors, but the broader message for borrowers is wider: higher rates, changing tax settings and softer property expectations are now influencing both lender caution and buyer confidence. - read more
November rate rise sharpens the test for Australian borrowers
05 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November decision to lift the cash rate by 25 basis points to 4.85 per cent has quickly shifted from monetary policy headline to household and business budgeting issue. Major lenders have moved to raise variable mortgage rates and savings rates from mid-November, reinforcing that borrowers now need to think less about a single repayment change and more about how much buffer remains in their overall loan commitments. - read more
Cash flow squeeze changes the loan conversation for small business
29 Oct 2026: Paige Estritori
Fresh evidence of delayed payments across Australian business is a timely warning for owners weighing up finance decisions. ABC News reported this week that small firms are dealing with a difficult mix of higher operating costs, regulatory changes and slower customer payments, while CreditorWatch’s September Business Risk Index showed one in 10 invoices over the past three months was more than 60 days overdue. - read more
Why hardship support is now a bigger loan issue
17 Sep 2026: Paige Estritori
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more


Finance Articles

Leveraging Loan Products for Accelerated Financial Freedom
Financial independence means having enough income to pay for one's living expenses without relying on a traditional job. In Australia, this concept is not just a dream but a necessity for many who aspire to a life free from financial stress. It offers the freedom to make choices about how you want to live your life, from retiring early to pursuing passions and interests without monetary constraints. - read more
Your Guide to Understanding Different Small Business Loan Options
In the bustling world of entrepreneurship, small business loans often act as the backbone that supports growth and sustainability. Understanding the array of loan options available is imperative for business owners in Australia, ensuring that they can make informed decisions that align with their objectives. - read more
How Loan Eligibility Is Assessed in Australia
Australian lenders assess loan applications by looking at income, expenses, credit history, existing debts, security, documentation and whether the loan appears affordable for the borrower's circumstances. - read more
Personal Loans in Australia: How They Work, Costs and Eligibility
Personal loans can help Australians fund expenses such as a car, renovation, travel, medical costs or debt consolidation. This guide explains how they work, the main costs, common eligibility factors and what to consider before applying. - read more

Business Loan Repayment Calculator

Business Loan Repayment Calculator

The Great Australian Side-Hustle

The Great Australian Side-Hustle

Loan Finance Online Weekly News Wrap

Loan Finance Online Weekly News Wrap

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.


Knowledgebase
Margin Call:
A demand by a broker that an investor deposit additional money or securities into the account to cover possible losses.